No Cost EMI in the Sale: What It Actually Costs and How to Check
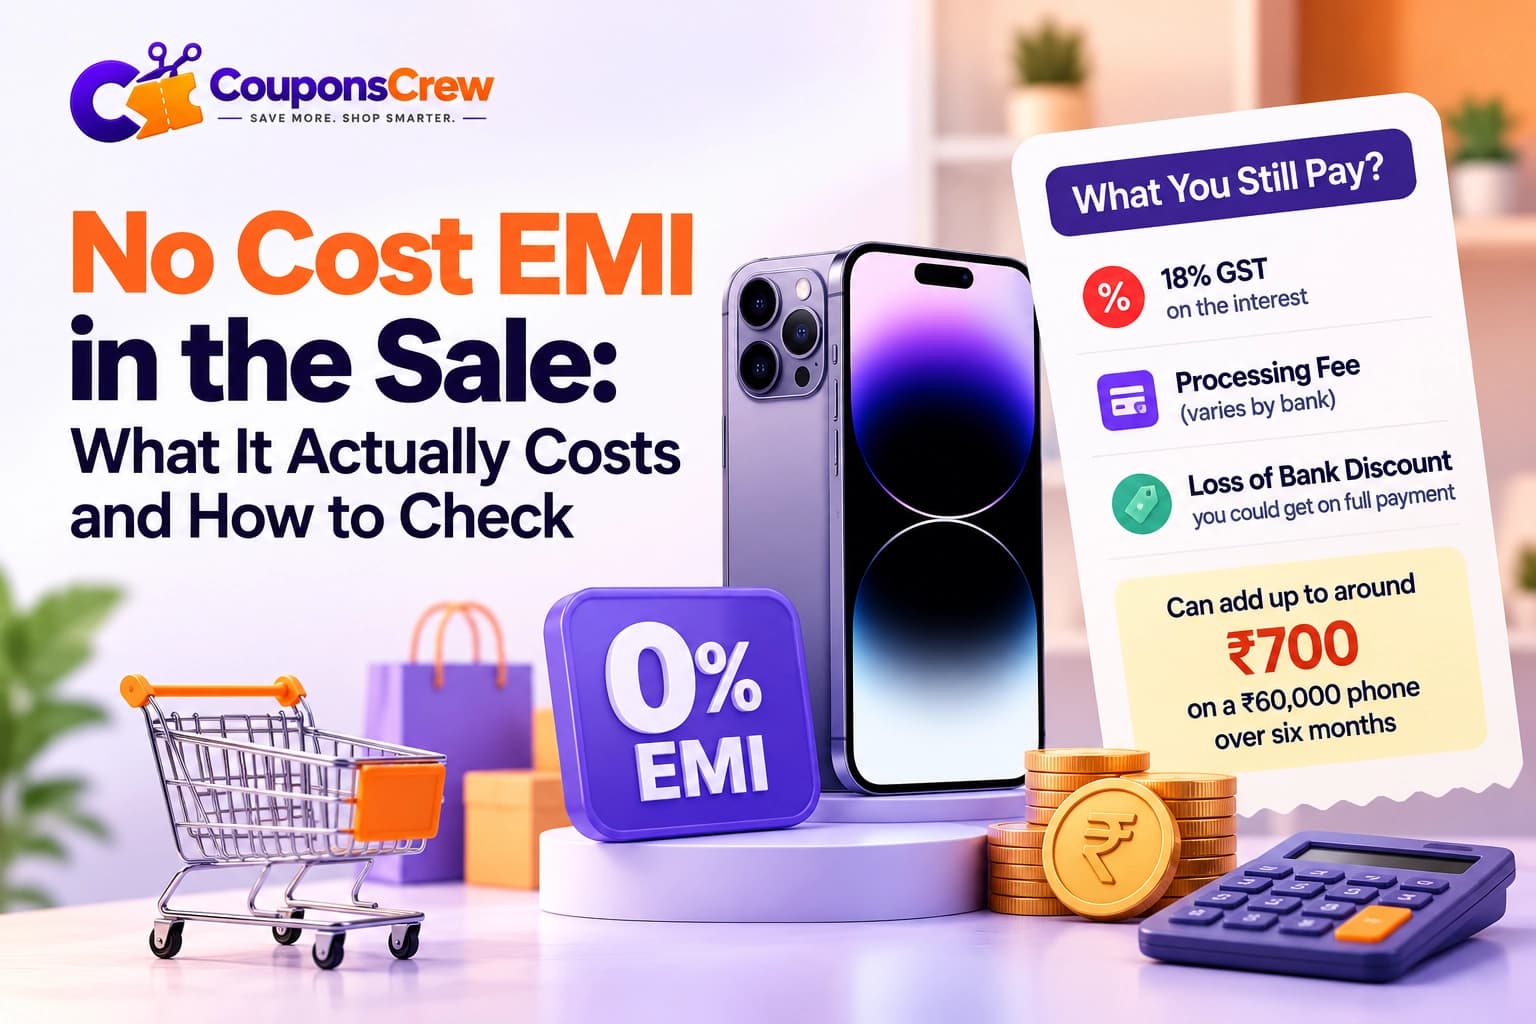
No Cost EMI usually costs a little, not nothing. The interest is real, but the seller covers it with an upfront discount. What you still pay is 18% GST on that interest, any processing fee your bank charges, and sometimes a bank discount you would have got by paying in full. On a ₹60,000 phone over six months, that can add up to around ₹700.
Last updated: 5 October 2026. Amazon Great Indian Festival starts on 8 October and Flipkart Big Billion Days on 9 October.
How No Cost EMI actually works
No Cost EMI is a normal EMI loan where the seller pays the interest for you. Your bank still charges interest on the purchase. The seller, or the brand, gives you a discount equal to that interest, so your monthly instalments add up to the product's price.
Here is what happens at checkout, step by step:
- You pick a product priced at, say, ₹60,000 and choose 6-month No Cost EMI.
- The seller gives an instant discount equal to the interest the bank will charge over six months.
- Your card is charged the discounted amount, and the bank converts it into an EMI loan.
- The bank adds interest to that loan. Your six instalments come to ₹60,000 in total.
- The bank also charges 18% GST on the interest, and in many cases a one-time processing fee. These are not covered by the discount.
The Reserve Bank of India made its position on "zero per cent" loans clear in a September 2013 circular to banks, saying that "zero per cent interest is non-existent". That is why banks still calculate interest on No Cost EMI purchases. The "no cost" part is the seller's discount, not the absence of interest.
Worked example: a ₹60,000 phone on No Cost EMI
The numbers below use two assumptions so you can see the mechanics: an annual interest rate of 15% and a processing fee of ₹199 plus GST. Your bank's actual rate and fee may be different; check them on the payment page before you confirm.
| Tenure | Monthly EMI | Seller discount (equal to interest) | GST on interest | Processing fee with GST | Extra you pay |
|---|---|---|---|---|---|
| 3 months | ₹20,000 | ₹1,469 | ₹264 | ₹235 | about ₹500 |
| 6 months | ₹10,000 | ₹2,540 | ₹457 | ₹235 | about ₹690 |
| 12 months | ₹5,000 | ₹4,603 | ₹829 | ₹235 | about ₹1,060 |
Two things stand out. First, the extra cost grows with the tenure, because a longer loan means more interest and more GST on it. Second, the extra cost is small compared with the price, roughly 1% to 2% here. No Cost EMI is not a trap; it simply is not free.
If your bank charges no processing fee for that offer, the extra cost drops to the GST alone. Some sale offers waive the fee, so check before you choose.
The bigger cost: the discount you might lose
In festive sales, the larger cost of EMI is often not the GST. It is the difference between the bank offer for full payment and the bank offer for EMI.
Bank instant discounts in big sales sometimes come with different terms for EMI. The percentage may be the same, but the cap or the minimum order can differ, and some offers apply only to full payment. This year, Amazon has said its 10% SBI card discount covers EMI transactions as well as full payments. Flipkart has listed Axis Bank and ICICI Bank card offers. In both cases, the exact caps and EMI terms appear on the product page during the sale.
Before you choose EMI, compare two numbers on the payment page:
- Final price if you pay in full, after the bank discount.
- Total of all EMIs plus processing fee and GST, after the bank discount for EMI.
If the full-payment option is cheaper by more than a few hundred rupees and you can afford it, EMI is costing you money. If the two are close, EMI is mainly a way to spread the payment, which can be worth it.
Other costs to check before choosing EMI
Your credit limit gets blocked
When you convert a purchase into EMI, the full amount is blocked on your card. It is released bit by bit as you pay each instalment. On a card with a ₹1 lakh limit, a ₹60,000 EMI purchase leaves you about ₹40,000 for everything else that month. If you plan to buy more in the same sale, check your available limit first.
Credit utilisation and your credit score
A large blocked amount raises your credit utilisation, the share of your limit you are using. High utilisation can lower your credit score for a while. Paying every instalment on time helps your score; a missed instalment hurts it and may cancel the No Cost benefit.
Closing the EMI early
If you pay off the EMI before the tenure ends, many card issuers charge a foreclosure fee, often a small percentage of the outstanding amount. You may also lose the No Cost benefit on the remaining months. Read the foreclosure terms if you think you might close early.
Returns and cancellations
If you return a product bought on EMI, the refund goes to your card, but the EMI conversion may not reverse cleanly. You may need to contact your bank to close the EMI, and the processing fee is often not refunded. Keep the order and EMI reference numbers until the return is complete.
EMI options you will see in this year's sales
| Option | How it works | What to check |
|---|---|---|
| Credit card No Cost EMI | Seller covers the interest; bank converts the purchase into EMI | GST on interest, processing fee, tenure options |
| Credit card standard EMI | You pay the interest yourself | Interest rate; often higher than you expect |
| Debit card EMI | Available to pre-approved customers of some banks | Eligibility shows only at checkout; similar fees apply |
| Cardless EMI and pay later | The platform or its lending partner gives you a credit line | Interest, late fees and whether the bank offer still applies |
On Amazon, No Cost EMI on eligible products has been reported to start from around ₹99 a day during the Great Indian Festival. Amazon also runs Amazon Pay Later. On Flipkart, the sale lists Flipkart EMI, Pay Later options and Super.money cashback. All of these have their own terms, so compare the final amount rather than the monthly figure.
For the full bank offer details of each sale, see our Amazon Great Indian Festival 2026 guide, our Big Billion Days 2026 guide and the side-by-side comparison of the two sales.
When No Cost EMI makes sense, and when it does not
It can make sense when:
- You would otherwise drain your savings or emergency fund to pay in full.
- The full-payment price and the EMI total are within a few hundred rupees of each other.
- The tenure is short and you are confident of paying every instalment on time.
- The bank waives the processing fee for the sale.
It is usually not worth it when:
- You lose a bigger bank discount by choosing EMI over full payment.
- The EMI would push your card close to its limit for months.
- You are buying several things on EMI at once, and the combined monthly amount strains your budget.
- You are using EMI to buy something you would not buy if you had to pay in full.
Quick checklist on the payment page
- Note the final price for full payment, after the bank discount.
- Select No Cost EMI and note the monthly amount and tenure.
- Look for the processing fee and the interest line in the EMI breakdown.
- Add GST on interest (18% of the interest shown) and the fee to the EMI total.
- Compare the two totals. Choose the lower one if you can afford it.
- Check your available credit limit after the EMI amount is blocked.
If the payment page does not show the interest or fee clearly, check your bank's EMI terms or the SMS and statement your bank sends after conversion, which list these charges.
Before the sale starts
Amazon's sale opens on 8 October and Flipkart's on 9 October, so there is time to check your card's EMI terms now. Log in to your bank's app, look up the processing fee for EMI conversions, and note your available limit. If you are buying a phone, our guide on whether to buy a phone now or wait for the sale explains how to work out the real sale price, including bank offers. The full list of sale dates is in our October 2026 sale calendar.
Coupon codes can lower the price before the EMI is calculated, which also lowers the interest and GST. Check the Amazon coupon code and Flipkart coupon code pages before checking out. For more ways to reduce the final bill, see our guide on how to save money shopping online in India.
Frequently Asked Questions
Disclaimer: This article explains how No Cost EMI generally works in India and uses illustrative numbers. It is not financial advice. Interest rates, fees and offer terms vary by bank, card and seller, and can change during a sale. Check the terms shown on the payment page and by your bank before converting a purchase into EMI.
Summary
No Cost EMI is a reasonable tool when it saves you from emptying your savings and costs only a few hundred rupees in GST and fees. It stops being a good deal when it costs you a bigger bank discount, or when the monthly amount makes it easy to spend more than you planned. Two minutes on the payment page comparing the totals is enough to know which one you are looking at.